Examining Token Utilization Strategies for Large-Scale Overseas Payment Approvals in Membership-Based Services
Written by Noah Braun · Sep 13, 2026
Examining Token Utilization Strategies for Large-Scale Overseas Payment Approvals in Membership-Based Services
Token utilization has become a central approach for handling large volumes of overseas payment approvals within membership-based services where recurring charges span multiple currencies and regulatory environments, and companies rely on these methods to replace primary account numbers with unique identifiers that maintain transaction continuity without exposing full card details during international routing.
Core Mechanics of Token Systems in Cross-Border Membership Billing
Payment networks generate tokens through issuer or processor vaults that map back to original credentials while restricting use to specific merchants or regions, which allows membership platforms to process approvals for subscribers located outside domestic markets without repeated transmission of sensitive data. Observers note that this mapping occurs at the point of initial authorization so subsequent charges draw from the stored token record, and data shows reduced exposure during settlement cycles that cross time zones and banking systems.
Scaling Token Strategies for High-Volume International Approvals
Large membership services often maintain separate token pools for different geographic corridors because approval rates vary when currencies fluctuate or when local regulations require additional verification steps, and organizations segment tokens by merchant category or by the issuing bank country to align with risk thresholds established by card networks. Researchers have documented how batch processing of tokenized requests supports thousands of simultaneous approvals during renewal periods, while single-message flows handle immediate onboarding for new members joining from overseas locations. Figures from industry reports indicate that services managing memberships across more than fifty countries achieve higher completion rates when they apply dynamic token routing that selects the least congested network path for each transaction.
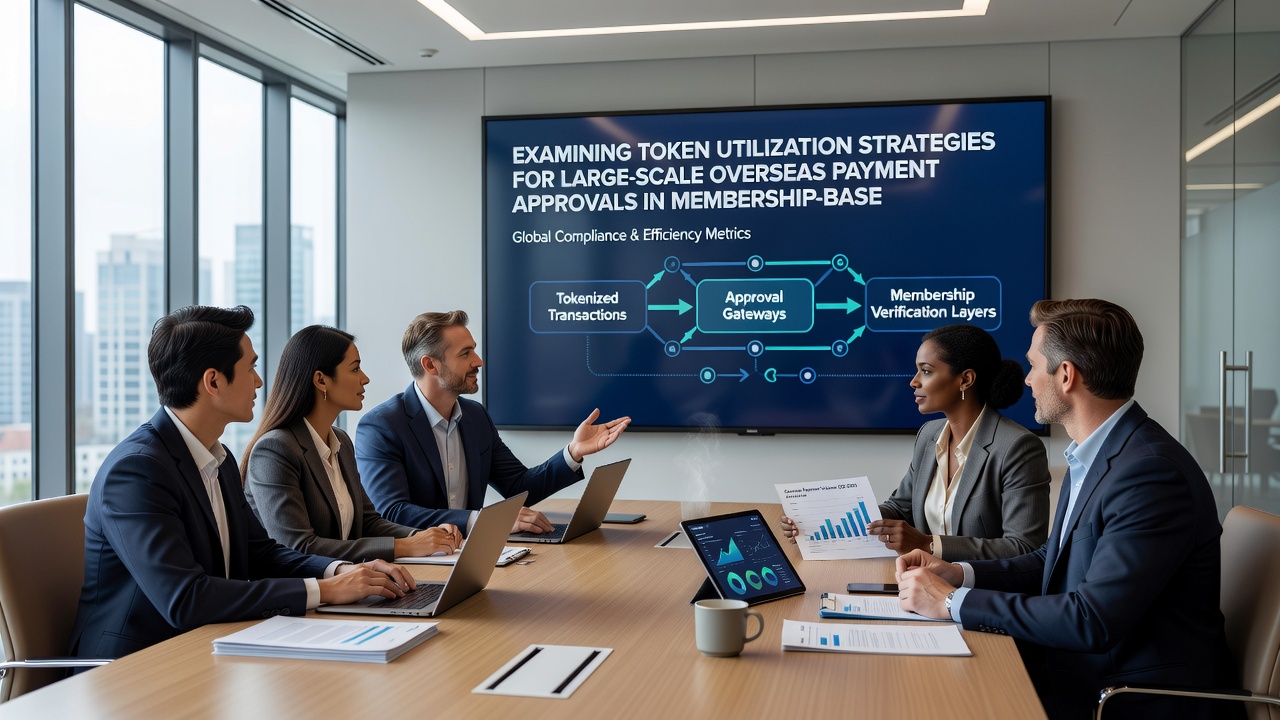
Integration with Regulatory Requirements Across Regions
Compliance frameworks in multiple jurisdictions require that tokenized data remain within approved storage locations and that access logs track every use for audit purposes, and membership operators coordinate these controls through centralized dashboards that flag any token activity originating from high-risk corridors. According to the PCI Security Standards Council, token service providers must demonstrate segmentation between production and test environments while supporting export controls that differ between the United States, the European Union, and Asia-Pacific markets. Data from the Reserve Bank of Australia reveals that organizations updating their token frameworks ahead of scheduled enhancements planned for September 2026 have reported measurable declines in declined authorizations tied to regional data residency rules.
Operational Patterns Observed in Membership Ecosystems
Services that combine network tokens with merchant-generated tokens often achieve greater flexibility because network tokens carry issuer-backed guarantees that survive card reissues, whereas merchant tokens allow finer control over subscription modifications such as plan upgrades or temporary holds. Those who have studied high-volume operations report that failover procedures automatically substitute an alternate token when the primary one encounters velocity limits during peak renewal windows, and case studies from global fitness and software membership providers illustrate how these substitutions maintain revenue continuity without manual intervention.
Security Controls and Risk Mitigation Techniques
Encryption of token vaults combined with limited-use credentials reduces the impact of any single breach, and monitoring systems apply machine learning models that compare current approval patterns against historical baselines for each token cohort. Evidence suggests that real-time alerts triggered by unusual cross-border sequences allow operators to suspend specific tokens before further attempts occur, while preserving the overall subscription base. Industry organizations such as the European Payments Council have published guidelines that emphasize testing token replacement workflows under simulated network outages to verify that membership charges resume without data re-entry.
Future Directions in Token Lifecycle Management
Emerging protocols aim to extend token validity across card network migrations so that a single token continues to function when underlying rails evolve, and pilot programs are evaluating shared token directories that multiple membership platforms could query to reduce duplicate storage. Observers note that these developments build on existing vault architectures rather than replacing them, and continued coordination between issuers, processors, and service providers supports the volume growth projected through the remainder of the decade.
Conclusion
Token utilization strategies provide structured pathways for managing overseas payment approvals at scale within membership services by combining secure mapping, regional segmentation, and regulatory alignment into repeatable operational flows. Continued refinement of these approaches supports reliable charge cycles as membership bases expand across borders and as data protection expectations evolve in parallel.